AI Makes Your Headcount a Guess. Your Lease Shouldn't Be a Bet.
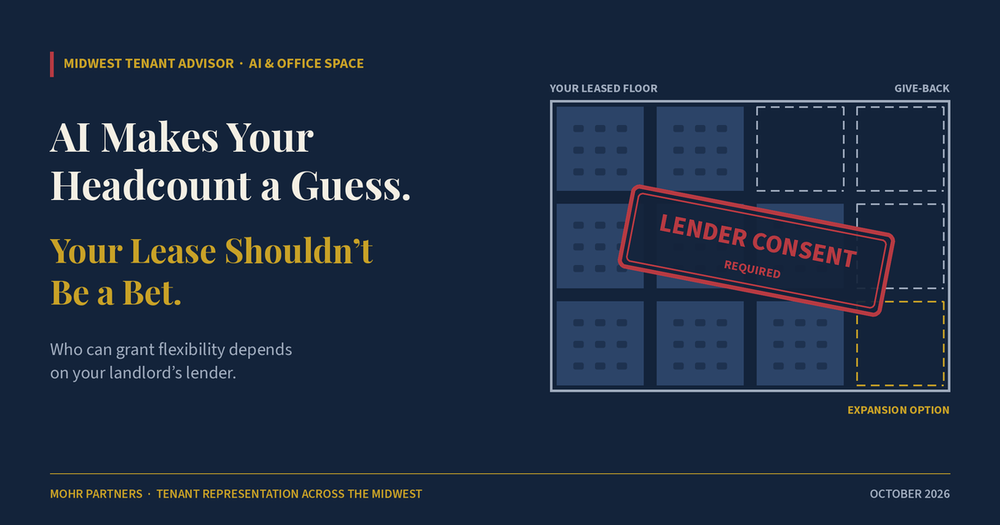
Every CEO signing an office lease this year is making a bet they cannot price. The lease runs seven to ten years. The headcount plan behind it runs maybe eighteen months, and AI and office space planning have never been further apart. Employers attributed more than 100,000 job cuts directly to AI in the first half of 2026, nearly a quarter of all announced cuts, up from under 5% last year. GM cut 500 to 600 IT roles this spring, many of them in Warren, Michigan. At the same time, the pool of AI-skilled workers grew 45% in a year. Some teams will shrink, others will grow, and nobody knows which in year four of your lease.
The standard advice is to build in flexibility. That advice is correct, and incomplete. It skips the question that decides whether you will actually get flexibility: can your landlord afford to give it?
Why AI and Office Space Planning Now Point to Flexibility
JLL's latest occupier research shows the tension clearly: 41% of corporate real estate leaders cite AI disruption as a top portfolio challenge, and 40% cite uncertainty about what AI means for their space requirements. When you cannot forecast demand, you buy options. In a lease, that means:
- Contraction rights: the right to give back a floor or a defined block at set points in the term.
- Early termination options: the right to exit after year five or seven for a fee.
- Expansion rights: a right of first offer or refusal on adjacent space, in case the AI build-out grows a team instead of shrinking it.
- Open sublease and assignment rights: no landlord recapture, so you can monetize space you no longer need. As we noted in our sublease market analysis, that exit route is only worth what the lease allows.
Every one of those clauses has a cost. Most tenants assume the landlord pays it. In practice, it is often the landlord's lender who decides.
Flexibility Shortens Your Landlord's Collateral
To a lender, your lease is not just rent. It is collateral. Appraisers and underwriters value an office building on the term and credit of its leases, and a ten-year lease with a termination right at year five is, for underwriting purposes, closer to a five-year lease. Grant enough of those and the building's weighted average lease term falls, its appraised value falls, and its loan-to-value rises.
Lenders protect against that contractually. CMBS loan documents typically require lender consent for leasing activity, especially on major leases, and the lender can usually withhold consent at its sole discretion. Some loan agreements require approval for any lease that includes a tenant termination right. The termination or non-renewal of a major lease is also a common trigger for cash management, which sweeps the property's cash flow to the lender. In other words, the flexibility clause you negotiate with the landlord may need sign-off from a party who is not at the table and has every incentive to say no.
Three Landlords, Three Different Answers
This is where the capital stack becomes a practical screening tool. On flexibility, landlords fall into three groups:
Low-basis or lightly leveraged owners. Owners who bought at a reset price or carry little debt can grant real options, because nobody above them in the capital stack has to approve. Expect fair pricing on termination fees and contraction rights.
Well-capitalized owners with long-term fixed debt. These owners can usually get lender consent, but they will price the option: a termination fee covering unamortized improvements and commissions plus several months of rent, and contraction rights limited to defined blocks.
Owners facing a 2026–2027 maturity. These landlords will often offer the richest rent concessions in the market, because they need occupancy for the refinance. They are also the least able to grant flexibility, because every option shortens the lease term their next lender will underwrite. As we explained in why your landlord's mortgage is your best leverage, debt pressure creates leverage, but it creates leverage on price, not on flexibility.
That is the trade most occupiers do not see: the landlord offering the cheapest rent may be the one structurally unable to give you an exit. If AI makes your headcount genuinely uncertain, the cheapest deal may be the most expensive one you sign.
Threats & Opportunities
Threats
- Options that need a lender's signature. A termination right agreed with the landlord but never approved by the lender can be challenged later. Make lender consent a condition of signing, and get the SNDA at the same time.
- Trading flexibility for rent. A dollar off face rent is worth far less than a year-five exit if your workforce shrinks 20%.
- Recapture clauses. A landlord's right to take back space you try to sublease defeats the purpose of sublease rights. Strike it or narrow it.
Opportunities
- Reset-basis buildings. Recently traded properties with modest debt can offer both competitive rent and genuine options.
- Shorter terms with renewal options. A five-year initial term with two renewal options often costs less than a ten-year lease with a termination right, and requires less lender approval.
- Diagnose before the LOI. Knowing your landlord's lender type and maturity date before proposals go out tells you which buildings can actually deliver flexibility.
Mohr Partners represents tenants only, across Ohio, Michigan, Indiana, Kentucky, and Western Pennsylvania. If AI is reshaping your workforce plan and your lease expires in the next 24 months, we will identify which landlords can grant real flexibility and what it should cost. Contact Scott Pollock at scott.pollock@mohrpartners.com or 440.821.8149.